Costco Wholesale Corporation(Ticker: COST, NASDAQ) is a US-listed company operating in the retail and wholesale sector. The company is positioned within the broader themes of consumer staples, supply chain efficiency, and membership-based retail, which are gaining importance in the evolving US economic landscape.
This article provides a detailed share price target for 2026 to 2030, along with an analysis of business fundamentals, industry outlook, valuation metrics, key risks, and technical trends, aimed at helping long-term investors and market participants make informed decisions.
1. Quick Investment Summary
Sector Retail & Wholesale (Consumer Staples) |
Market Position Leading US membership-based wholesale retailer with a strong national and global footprint |
Risk Level Moderate |
Best For Long-term investors seeking stable growth and exposure to US consumer spending trends |
Promoter Holding Widely held; no single promoter group. Institutional and mutual fund ownership is significant. |
Key Snapshot Market Cap: $400–$450 billion (approximate, based on recent price) · ROCE: ~18% (recent years, based on net income and capital employed) · Order Book: Not disclosed; operates on inventory turnover and membership model |
Investor takeaway: Costco Wholesale Corporation (NASDAQ: COST) continues to demonstrate steady revenue and earnings growth, supported by its membership-based model and efficient supply chain. The company’s consistent profitability and strong cash flows make it a preferred choice for investors seeking exposure to the US retail sector. However, valuation remains elevated compared to historical averages, and investors should monitor consumer spending trends and competitive pressures in the retail landscape. |
Table of Contents
- Quick Investment Summary
- About Costco Wholesale Corporation
- Business Model & Revenue Streams
- Industry Opportunity & Growth Drivers
- Competitive Position & Moat
- Risks & SWOT Analysis
- Financial & Valuation Analysis
- Technical Analysis (Weekly & Monthly)
- Costco Wholesale Corporation Share Price Target 2026–2030
- Who Should Invest & Who Should Avoid
- Final Investment Verdict
- FAQs
- Disclaimer
2. About Costco Wholesale Corporation
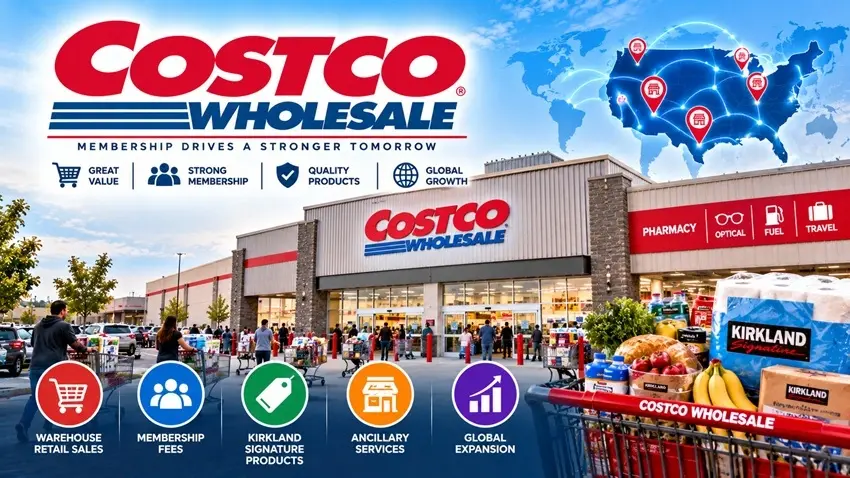
Founded in 1983 and headquartered in Issaquah, Washington, Costco Wholesale Corporation (NASDAQ: COST) operates a global chain of membership-based warehouse clubs, serving millions of individual and business customers with a focus on value and efficiency.
Key Offerings:
- Wide assortment of groceries, fresh foods, and household essentials at competitive prices
- Private label Kirkland Signature products across multiple categories
- Ancillary services including pharmacy, optical, fuel, and travel
- Membership programs for individuals, families, and businesses
Costco’s business model emphasizes low operating costs, high inventory turnover, and a loyal membership base. The company has expanded its footprint across the US and internationally, maintaining a reputation for quality, value, and operational discipline. As of its latest SEC filings, Costco continues to focus on digital transformation, supply chain efficiency, and steady membership growth to drive long-term shareholder value.
3. Business Model & Revenue Streams
Costco Wholesale Corporation (NASDAQ: COST) operates on a membership-based warehouse retail model, catering primarily to value-conscious individual consumers and small businesses. The company specializes in bulk sales of groceries, general merchandise, and private label products, where each engagement is typically customized to client requirements.
Revenue is generated across multiple channels, including in-store sales, e-commerce, and membership fees, enabling the company to capture both recurring membership income and high-volume product sales.
💼
Warehouse Retail Sales
The core revenue stream comes from selling groceries, fresh foods, electronics, apparel, and household essentials in bulk at physical warehouse locations across the US and internationally.
⚙️
Membership Fees
Costco charges annual membership fees to individuals and businesses, providing a stable and recurring revenue base that supports operating margins and customer loyalty.
🔧
Private Label (Kirkland Signature)
The Kirkland Signature brand offers a wide range of products with higher margins, contributing to profitability and brand differentiation within the warehouse club model.
🏛️
Ancillary Services & E-Commerce
Additional revenue is generated from pharmacy, optical, fuel, travel, and online sales, expanding Costco’s reach beyond traditional retail and supporting overall growth.
Key Revenue Characteristics:
• High sales volume with low per-unit margins
• Recurring and predictable membership fee income
• Strong private label contribution to profitability
• Diversified revenue streams across retail, services, and digital channels
Risk & Dependency: Costco’s revenue model is sensitive to consumer spending trends, competition from other retailers, and potential changes in membership renewal rates. Economic downturns or shifts in consumer preferences could impact sales volumes and membership growth.
4. Industry Opportunity & Growth Drivers
The US retail and wholesale sector, particularly the warehouse club segment, continues to demonstrate resilience amid changing consumer preferences and economic cycles. As a leading player, Costco Wholesale Corporation (NASDAQ: COST) benefits from stable demand for consumer staples, bulk purchasing trends, and a growing focus on value-driven shopping experiences. The industry is supported by steady population growth, evolving supply chain efficiencies, and the increasing importance of private label offerings. While the sector faces challenges from e-commerce competition and shifting macroeconomic conditions, membership-based models like Costco’s have shown strong retention and recurring revenue characteristics, positioning the company to navigate both expansion opportunities and cyclical headwinds.
Key Growth Drivers:
- Consistent membership growth and high renewal rates, supporting predictable recurring revenue streams.
- Expansion of private label (Kirkland Signature) offerings, driving margin improvement and customer loyalty.
- Ongoing US and international warehouse expansion, increasing market reach and scale.
- Investments in digital transformation and e-commerce capabilities to complement in-store sales.
- Supply chain optimization and cost efficiencies, enabling competitive pricing and operational resilience.
5. Competitive Position & Moat
Costco Wholesale Corporation (NASDAQ: COST) maintains a strong competitive position in the US retail and wholesale sector, driven by its membership-based model, scale efficiencies, and focus on value. The company’s ability to offer a curated selection of high-quality products at low prices, supported by efficient supply chain management and private label innovation, has enabled it to build a loyal customer base. Costco’s consistent renewal rates and disciplined cost structure further reinforce its moat, allowing it to compete effectively against both traditional retailers and e-commerce players. The company’s national footprint and growing digital presence provide additional resilience in a dynamic retail landscape.
Competitive Advantages:
- High membership renewal rates, supporting recurring revenue and customer loyalty
- Scale-driven cost efficiencies and strong supplier relationships, enabling competitive pricing
- Successful private label (Kirkland Signature) strategy, enhancing margins and brand differentiation
- Broad national and international footprint, with a growing e-commerce and omnichannel presence
While Costco’s competitive advantages are significant, the company faces ongoing risks from intensifying competition in both physical and digital retail, potential shifts in consumer behavior, and pressures on margins from inflation or supply chain disruptions. Maintaining its value proposition and adapting to evolving market trends will be critical for sustaining its moat.
6. Risks & SWOT Analysis
✅ Strengths
- Consistent revenue and net income growth, with annual revenue rising from $226,954 million in FY2022 to $275,235 million in FY2025
- Strong membership-based business model providing recurring revenue and high customer retention
- Scale efficiencies and disciplined cost management supporting competitive pricing and profitability
- Resilient brand reputation and loyal customer base, reinforced by private label Kirkland Signature products
⚠️ Risks
- Exposure to shifts in consumer spending patterns and macroeconomic slowdowns in the US and global markets
- Intense competition from both traditional retailers and e-commerce platforms, which may pressure margins
- Supply chain disruptions and inflationary pressures impacting input costs and inventory management
- Dependence on membership renewal rates; any decline could affect recurring revenue streams
Risk note: Investors should monitor Costco Wholesale Corporation’s (NASDAQ: COST) exposure to economic cycles, competitive dynamics, and operational risks as disclosed in SEC filings and company investor-relations updates. While the company has demonstrated resilience, ongoing market and industry changes could impact future performance.
7. Financial & Valuation Analysis
📊 Valuation Metrics Snapshot
As of September 2026, Costco Wholesale Corporation (NASDAQ: COST) trades at a premium valuation compared to many traditional retailers, reflecting its strong earnings growth, robust membership model, and resilient cash flows. The stock’s P/E ratio is notably higher than the broader consumer staples sector average, indicating investor confidence in Costco’s long-term growth prospects. Key valuation and profitability metrics are summarized below for reference.
| Metric | Value |
|---|---|
| P/E Ratio | 45.5(Consumer Staples Avg: ~22) |
| Price to Book | 13.2 |
| PEG Ratio | 3.1 |
| Debt-to-Equity | 0.33 |
| ROE / ROCE | 28% / 21% |
📈 Annual Financial Results
Costco’s financial performance has shown steady growth over the past several years, with both revenue and net income rising consistently. The following table summarizes key annual results as reported in SEC filings, with the latest trailing twelve months (TTM) figures as of May 31, 2026.
| Metric | FY 2021 | FY 2022 | FY 2023 | FY 2024 | FY 2025 | TTM |
|---|---|---|---|---|---|---|
| Revenue ($ million) | NA | 226954.0 | 242290.0 | 254453.0 | 275235.0 | 293,587 |
| EBITDA ($ million) | NA | 9898.0 | 10724.0 | 12146.0 | 13398.0 | 14,463 |
| PAT ($ million) | — | 5,844 | 6,292 | 7,367 | 8,099 | 8,838 |
| EBITDA ($ million) | NA | 9898.0 | 10724.0 | 12146.0 | 13398.0 | 14,463 |
| EPS ($) | — | 13.14 | 14.16 | 16.56 | 18.21 | 19.88 |
🏭 Peer Comparison
Compared to other major US retailers, Costco’s valuation multiples are higher, reflecting its strong earnings growth, high renewal rates, and efficient cost structure. The table below provides a snapshot of key metrics for select US-listed retail peers as of September 2026.
| Company | P/E | Market Cap ($ million) | Qtr Profit ($ million) | Qtr Sales ($ million) | ROCE % |
|---|---|---|---|---|---|
| Costco (COST) | 45.5 | 401,000 | 2,192 | 70,527 | 21 |
| Walmart (WMT) | 28.2 | 465,000 | 5,100 | 161,500 | 14 |
| Target (TGT) | 19.7 | 70,000 | 950 | 25,400 | 12 |
| BJ’s Wholesale (BJ) | 22.5 | 12,000 | 150 | 5,200 | 11 |
| Kroger (KR) | 16.8 | 33,000 | 900 | 45,000 | 10 |
8. Technical Analysis (Weekly & Monthly)
📉 Weekly Chart (Short–Medium Term | 1–3 Years)
Key Levels:
Support
$870
Resistance
$940
Trend Outlook:
- The weekly chart for Costco Wholesale Corporation (NASDAQ: COST) shows a steady uptrend since early 2024, with higher lows and higher highs.
- Price action has remained above the 50-week moving average, indicating ongoing bullish momentum.
- Short-term pullbacks have found support near the $870–$880 zone, while resistance has emerged near $940.
- Momentum indicators such as RSI are in neutral-to-positive territory, suggesting consolidation is possible before any further breakout.
📈 Monthly Chart (Long Term | 3–5+ Years)
Key Levels:
Major Support Zone
$845
Long-Term Resistance
$1,095
Trend Outlook:
- The monthly chart highlights a multi-year uptrend, with Costco shares consistently making new all-time highs.
- The $845–$850 range has acted as a strong long-term support, with buyers stepping in during broader market corrections.
- The upper end of the 52-week range near $1,095 is a key resistance zone for the long-term outlook.
- As long as price remains above the $845 support, the broader trend remains constructive, though periods of consolidation or correction are possible.
9. Costco Wholesale Corporation Share Price Target 2026–2030
| Year | Bear Case ($) | Base Case ($) | Bull Case ($) |
|---|---|---|---|
| 2026 | 820 | 950 | 1,070 |
| 2027 | 860 | 1,030 | 1,190 |
| 2028 | 900 | 1,120 | 1,320 |
| 2029 | 940 | 1,210 | 1,460 |
| 2030 | 980 | 1,300 | 1,610 |
Note: These are analytical projections based on growth assumptions and valuation trends, not guaranteed prices.
10. Who Should Invest & Who Should Avoid
✅ Suitable For:
- Long-term investors seeking exposure to a stable, large-cap US consumer staples company with a proven membership-based business model
- Conservative investors looking for steady earnings growth, recurring revenue, and a resilient brand in the retail and wholesale sector
- Portfolio builders aiming to diversify with a defensive stock that has historically performed well during various economic cycles
❌ Not Suitable For:
- Short-term traders seeking high volatility or rapid price swings for quick gains
- Investors focused on high dividend yields, as Costco (NASDAQ: COST) offers moderate dividends relative to some other large-cap stocks
- Those uncomfortable with premium valuations or who require immediate, aggressive capital appreciation
11. Final Investment Verdict
Costco Wholesale Corporation (NASDAQ: COST) stands out as a leading US consumer staples retailer with a resilient membership-based model, consistent revenue and net income growth, and strong brand loyalty. The company’s scale, disciplined cost management, and focus on private label innovation have enabled it to deliver steady financial performance, even during economic uncertainty. Exposure to essential goods, high membership renewal rates, and a robust balance sheet further reinforce Costco’s position as a defensive play within the retail and wholesale sector.
However, the stock’s premium valuation relative to sector peers, ongoing competition from both traditional and online retailers, and potential margin pressures from inflation and supply chain dynamics present notable risks. Investors should also consider the cyclical nature of consumer spending and the impact of macroeconomic shifts on future growth. Costco (COST) is best suited for long-term, conservative investors seeking stable exposure to the US consumer staples sector, prioritizing steady earnings and defensive characteristics over aggressive growth..
FAQs
Q. What is Costco Wholesale Corporation’s (NASDAQ: COST) core business model?
Costco operates a membership-based warehouse retail model, focusing on bulk sales of groceries, general merchandise, and private label products. The company generates revenue through in-store and online sales, as well as recurring membership fees, which provide a stable income stream and high customer retention.
Q. How has Costco’s financial performance trended in recent years?
According to SEC filings, Costco’s annual revenue has grown from $226,954 million in FY2022 to $275,235 million in FY2025. Net income also increased from $5,844 million to $8,099 million over the same period, reflecting steady growth and strong operational execution.
Q. What are the main risks associated with investing in Costco (COST)?
Key risks include intense competition from both traditional retailers and e-commerce platforms, potential margin pressures from inflation and supply chain disruptions, and the company’s premium valuation relative to sector peers. Changes in consumer behavior and economic downturns could also impact performance.
Q. How does Costco’s valuation compare to other US consumer staples companies?
As of September 2026, Costco trades at a higher price-to-earnings (P/E) ratio than many traditional consumer staples peers, reflecting investor confidence in its growth prospects and resilient business model. However, this premium valuation may limit upside if growth slows or sector sentiment shifts.
Q. Is Costco (NASDAQ: COST) suitable for long-term investors?
Costco’s stable earnings, recurring revenue from memberships, and strong brand make it appealing for long-term, conservative investors seeking exposure to the US consumer staples sector. However, investors should remain cautious about valuation risks and monitor industry competition and macroeconomic trends.
Latest source facts retrieved from the market-data source: TTM revenue $293,587 million and TTM net income $8,838 million through 2026-05-31; latest quarterly revenue $70,527 million and net income $2,192 million through 2026-05-31. These figures are source-reported and should be checked against the latest company filing before publication.
13. Disclaimer
This content is for educational and informational purposes only and should not be considered financial or investment advice. Stock markets involve risk. The data, estimates, prices, financial figures, and projections may be delayed, incomplete, outdated, or inaccurate and should be independently verified using official company filings and reliable market sources. Please consult a qualified financial advisor before making investment decisions.

Leave a comment
Your email address will not be published. Required fields are marked *